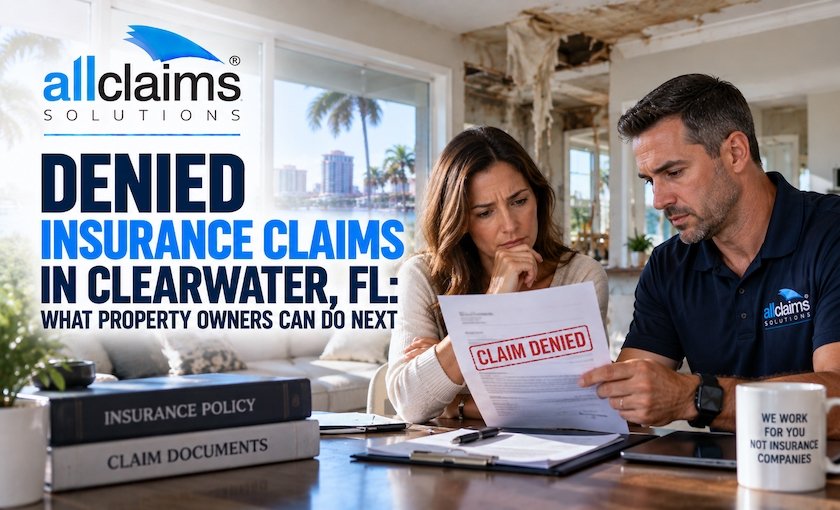
Having an insurance claim denied can be frustrating, especially after your Clearwater property has suffered damage from a storm, hurricane, fire, water leak, roof problem, or another covered event.
Receiving a denial letter does not necessarily answer every question about your claim.
The important next step is to understand why the insurance company denied the claim, what the policy says, what evidence supports the loss, and what options may be available.
Depending on the circumstances, a denied claim may involve questions about coverage, the cause of damage, the extent of the loss, documentation, policy exclusions, claim deadlines, or other issues.
This guide explains what Clearwater property owners should know after receiving a denied insurance claim and how to approach the next steps.
What Does It Mean When an Insurance Claim Is Denied?
An insurance claim denial generally means the insurer has determined that it will not pay the claim, or a particular portion of the claim, based on its interpretation of the policy and the circumstances of the loss.
The reason can vary considerably from one claim to another.
For example, an insurer may determine that:
- The cause of damage is not covered
- A policy exclusion applies
- The damage occurred gradually
- The property owner did not provide sufficient documentation
- The claimed damage is not related to the reported event
- Certain damage falls outside the policy’s coverage
- The policy conditions were not satisfied
- The insurer’s investigation did not establish covered damage
A denial should therefore be evaluated based on the specific explanation provided by the insurer, rather than assuming that every denied claim has the same issue.
Why Are Insurance Claims Denied in Clearwater, FL?
Clearwater property owners can experience many different types of losses, including hurricane, storm, wind, water, fire, roof, and other property damage.
Some of the most common issues involved in disputed or denied claims include the following.
1. Disagreement About the Cause of Damage
The insurer may determine that the cause of the loss is excluded or different from what the property owner reported.
For example, a dispute could involve whether damage resulted from:
- Wind
- Rain
- Flood
- Plumbing
- Roof deterioration
- Storm-created opening
- Long-term water intrusion
- Another excluded condition
The cause of loss can be one of the most important issues in an insurance claim.
2. Gradual Damage
Insurance policies may distinguish between sudden damage and damage that developed over an extended period.
Examples may include:
- Long-term leaks
- Deterioration
- Repeated moisture intrusion
- Rot
- Corrosion
- Wear and tear
However, the precise treatment depends on the policy and circumstances.
Property owners should not assume that a reference to “gradual damage” automatically resolves every aspect of a claim.
3. Lack of Documentation
Insurance claims require evidence.
An insurer may request information such as:
- Photographs
- Videos
- Repair estimates
- Invoices
- Receipts
- Contractor reports
- Plumbing reports
- Roof inspection reports
- Fire department reports
- Personal property inventories
Florida’s Department of Financial Services recommends documenting damage, taking photographs, making reasonable temporary repairs, keeping an inventory of damaged property, and saving receipts.
4. Policy Exclusions
Every insurance policy contains limitations and exclusions.
A denial may reference a specific exclusion or limitation.
That is why it is important to review:
- The declarations page
- Coverage forms
- Endorsements
- Exclusions
- Deductibles
- Applicable limits
- Definitions
- Conditions
Rather than focusing only on the denial letter, compare the insurer’s explanation with the actual policy language.
5. Disagreement About the Extent of Damage
Not every claim dispute is a complete denial.
Sometimes the insurer accepts that a covered loss occurred but disputes how much damage exists or what it will cost to repair.
For example, an insurer may acknowledge storm damage but disagree about:
- Roof repairs
- Interior water damage
- Drywall replacement
- Flooring
- Cabinets
- Structural repairs
- Personal property
- Additional living expenses
In these situations, the issue may be more accurately described as an underpaid or partially disputed insurance claim rather than a complete denial.
Denied vs. Underpaid Insurance Claims
These are important search and claim-status distinctions.
Denied Insurance Claim
The insurer determines that it will not provide payment for the claim or a particular portion of it.
Underpaid Insurance Claim
The insurer accepts some responsibility for the loss but the policyholder believes the payment or scope does not adequately reflect the covered damage.
Reopened Claim
Under current Florida law, a reopened claim is a claim previously closed by the insurer that is reopened at the insured’s request for additional costs for loss or damage previously disclosed to the insurer.
Supplemental Claim
Florida law defines a supplemental claim as additional loss or damage from the same peril under the circumstances specified in the statute.
Understanding this distinction can help property owners describe their situation more accurately.
What Should You Do After an Insurance Claim Is Denied?
If your Clearwater insurance claim has been denied, avoid making decisions based solely on the first page of the denial letter.
Instead, work through the following steps.
Step 1: Read the Denial Letter Carefully
Look for the specific reason given by the insurance company.
The letter may reference:
- A policy exclusion
- A coverage limitation
- A specific policy provision
- Cause of loss
- Insufficient evidence
- Late notice
- Wear and tear
- Lack of documentation
Save the complete letter and all attachments.
Step 2: Request the Relevant Claim Documents
Depending on the circumstances, gather copies of:
- Your insurance policy
- Declarations page
- Endorsements
- Insurance estimate
- Adjuster’s report
- Photographs
- Engineer or specialist reports
- Recorded statements
- Correspondence
- Claim correspondence
- Repair estimates
Having the complete claim file can make it easier to understand the insurer’s position.
Step 3: Compare the Denial With the Policy
The most important question is not simply:
“Why did they deny my claim?”
It is:
“Does the reason for the denial correspond with the actual policy language and the facts of the loss?”
For example, if the insurer cites an exclusion, review the wording of that exclusion and any related provisions.
Coverage disputes can involve specific policy language, definitions, exceptions, endorsements, and facts that are difficult to evaluate from a short denial letter alone.
Step 4: Document the Property Damage
If you have not already done so, organize evidence of the loss.
Include:
Photos
Take photographs of:
- Exterior damage
- Roof damage
- Interior damage
- Ceilings
- Walls
- Floors
- Cabinets
- Personal property
Videos
Videos can help show:
- The overall condition of the property
- Water intrusion
- Active leaks
- Damaged areas
- The relationship between different affected rooms
Repair Documentation
Keep:
- Contractor estimates
- Restoration invoices
- Emergency mitigation records
- Plumbing reports
- Roofing reports
- Inspection reports
Step 5: Preserve Damaged Property When Appropriate
Don’t automatically throw away damaged belongings.
Florida DFS advises property owners to document damaged items and not discard them without prior approval from the insurance company.
When practical, photograph and inventory damaged items before disposal or replacement.
Step 6: Look for Additional or Previously Overlooked Damage
Some property damage is not immediately visible.
For example:
Water Damage
Moisture may exist behind walls or underneath flooring.
Roof Damage
A roof inspection may identify damage that was not obvious from the ground.
Fire Damage
Smoke, soot, odor, and heat-related damage may extend beyond the visibly burned area.
Storm Damage
Wind or rain may create damage in multiple areas of the structure.
A more complete inspection can therefore be important when evaluating a disputed claim.
How Long Do You Have to Deal With a Denied Insurance Claim in Florida?
This is an important issue for Clearwater property owners.
Under current Florida Statute §627.70132, notice of a claim or reopened claim generally must be provided within one year after the date of loss, while a supplemental claim generally must be noticed within 18 months. The statute also defines special treatment for certain weather-related losses and says these deadlines do not eliminate other applicable limitations on civil actions for timely claims.
These are statutory deadlines, and the policy itself can also contain notice requirements.
Do not wait simply because an insurer has already denied your claim.
If you believe additional action may be necessary, review the dates and documents promptly.
What If Your Clearwater Claim Was Denied After a Hurricane or Storm?
Storm-related claims can involve multiple types of damage.
For example:
Hurricane / Storm
↓
Roof damage
↓
Water intrusion
↓
Interior damage
↓
Mold or secondary damage
An insurer may agree that some damage occurred while disputing:
- The cause
- The extent
- Whether damage is related to the storm
- Whether certain components are excluded
- The amount required for repairs
This is one reason documentation of the cause, timing, and scope of damage is important.
What If My Water Damage Claim Was Denied?
Water damage claims can be particularly complicated because the source of the water matters.
For example, a policy may treat damage differently depending on whether it resulted from:
- A burst pipe
- Plumbing failure
- Roof intrusion
- Storm water
- Flooding
- Sewer backup
- Appliance failure
- Long-term seepage
Your existing Clearwater content on Water Damage Insurance Claims and Water Damage vs. Flood Damage can provide additional information here.
Internal links recommended:
- Water Damage Insurance Claims in Clearwater, FL
- Water Damage vs. Flood Damage in Clearwater, FL
What If My Roof Damage Claim Was Denied?
Roof claims can involve disagreements about:
- Wind damage
- Storm damage
- Age of the roof
- Wear and tear
- Maintenance
- Pre-existing conditions
- Interior water damage
- The extent of repairs required
If the insurer denies the claim based on the cause or condition of the roof, carefully review the inspection report and policy language.
Related resource:
Roof Damage Insurance Claims in Clearwater, FL
Can a Public Adjuster Help With a Denied Insurance Claim?
A public adjuster represents the policyholder, not the insurance company.
Florida’s Department of Financial Services explains that public adjusters represent policyholders by adjusting and presenting claims to insurers and must be licensed by the state.
Depending on the circumstances, a public adjuster may help with:
- Reviewing the insurance policy
- Inspecting property damage
- Documenting the scope of loss
- Preparing claim documentation
- Reviewing the insurer’s estimate
- Identifying potentially overlooked damage
- Organizing supporting evidence
- Communicating with the insurance company
- Presenting the claim
- Negotiating with the insurer
A public adjuster cannot guarantee that a denied claim will be approved or that a specific settlement amount will be paid.
When Should You Consider Hiring a Public Adjuster?
There is no single rule that applies to every claim.
Professional claim assistance may be worth considering when:
- The damage is extensive
- The insurer has denied the claim
- The insurer has partially denied the claim
- The claim appears significantly underpaid
- The cause of loss is disputed
- The scope of damage is disputed
- Additional damage has been discovered
- The claim involves substantial documentation
- You are having difficulty understanding the insurer’s estimate or position
For smaller or straightforward losses, a property owner may decide to handle the claim independently.
The appropriate approach depends on the circumstances.
Public Adjuster vs. Insurance Company Adjuster
It is important to understand the difference.
Insurance Company Adjuster
The insurance company’s adjuster investigates and evaluates the claim on behalf of the insurer.
Public Adjuster
A public adjuster represents the policyholder.
Their role may include preparing, documenting, presenting, and negotiating the policyholder’s claim.
Florida DFS specifically states that a public adjuster does not work for or represent the insurance company.
What Other Options Are Available After a Claim Denial?
A denied claim does not mean that there is only one possible next step.
Depending on the circumstances, a property owner may consider:
Requesting Additional Information
Ask the insurer to explain the basis for the denial and identify the relevant policy provisions.
Providing Additional Documentation
Additional photographs, estimates, reports, or other evidence may help clarify the claim.
Seeking Professional Claim Assistance
A licensed public adjuster may help evaluate and present the claim.
Requesting State Assistance
The Florida Department of Financial Services Consumer Services Division accepts insurance concerns and can review whether an insurer followed applicable statutes and administrative rules. DFS states that consumers should first give the insurance company an opportunity to resolve the issue and keep detailed records of communications.
Florida DFS also offers mediation for certain eligible property insurance claim disputes, including some disputes involving claim denials and unsatisfactory settlement offers. Eligibility requirements apply.
Consulting an Insurance Attorney
If the dispute involves legal rights, policy interpretation, litigation, or other legal issues, an attorney can provide legal advice specific to the situation.
What Should You Avoid After a Claim Denial?
A few mistakes can make a complicated claim even more difficult.
Don’t Ignore the Denial Letter
Deadlines can matter.
Don’t Destroy Documentation
Keep your policy, estimates, photographs, correspondence, and reports organized.
Don’t Exaggerate Damage
Insurance claims should accurately reflect the property damage and supporting evidence.
Don’t Assume the First Estimate Is the Final Word
A disputed scope or estimate can be reviewed against the documented condition of the property.
Don’t Wait Until the Deadline
Florida currently provides specific statutory notice periods for claims, reopened claims, and supplemental claims.
How All Claims Solutions Can Help With Denied Insurance Claims in Clearwater
At All Claims Solutions, we represent Florida property owners in the insurance claim process.
If your Clearwater property insurance claim has been denied, partially denied, or appears to have been underpaid, our team can help review the circumstances of the loss, document the property damage, organize claim information, and communicate with the insurance company.
Our approach is focused on understanding:
What happened?
What was damaged?
What does the policy provide?
What documentation supports the claim?
Every insurance claim is different, and no outcome can be guaranteed.
Received a Denied Insurance Claim in Clearwater?
Don’t assume that the denial letter is the end of the conversation.
Contact All Claims Solutions for a free insurance claim evaluation and learn what options may be available for your property damage claim.
Denied Insurance Claim Checklist
If your claim has been denied, gather the following:
☐ Insurance denial letter
☐ Complete insurance policy
☐ Declarations page
☐ Policy endorsements
☐ Claim number
☐ Date of loss
☐ Photos and videos
☐ Insurance estimate
☐ Adjuster’s report
☐ Contractor estimates
☐ Restoration reports
☐ Inspection reports
☐ Fire or police report, if applicable
☐ Personal property inventory
☐ Repair invoices
☐ Temporary repair receipts
☐ All correspondence with the insurer
☐ Documentation of additional damage
☐ Notes from conversations with adjusters
Keeping these documents organized can make the claim easier to evaluate.
Frequently Asked Questions About Denied Insurance Claims in Clearwater, FL
Start by reviewing the denial letter, gathering your policy and claim documents, documenting the property damage, and identifying the specific reason for the denial. Depending on the circumstances, you may also consider professional claim assistance, Florida DFS resources, mediation, or legal advice.
The appropriate process depends on the insurer, policy, type of dispute, and circumstances. Start by reviewing the denial and asking the insurer to explain the basis of its decision. Additional documentation may also be relevant.
A licensed public adjuster can represent the policyholder in adjusting and presenting an insurance claim. Depending on the circumstances, they may help document the loss, prepare claim materials, review estimates, and communicate with the insurer.
A partial payment may indicate a disagreement about the scope, cause, valuation, or coverage of the damage. Review the insurer’s estimate against the documented property damage and policy provisions.
The answer depends on the circumstances and how the claim was handled. Florida law specifically defines reopened claims and supplemental claims, with different statutory notice periods.
Under current Florida law, a claim or reopened claim generally must be noticed within one year after the date of loss, while supplemental claims generally have an 18-month notice period. The policy’s requirements and the specific circumstances of the loss also matter.
The Florida Department of Financial Services can assist consumers with insurance concerns and can review whether an insurer followed applicable Florida statutes and administrative rules. DFS also offers mediation for certain eligible property insurance disputes.
They have different roles. A public adjuster represents the policyholder in the insurance claim process. An attorney provides legal advice and can handle legal disputes and litigation. The appropriate professional depends on the nature of the problem.
Need Help With an Insurance Claim in Clearwater?
Get a Free Insurance Claim Evaluation in Clearwater, FL
Speak with All Claims Solutions today →
This article is for general informational purposes only and does not constitute legal advice or a determination of insurance coverage. Insurance coverage depends on the specific policy, endorsements, exclusions, deductibles, limits, and circumstances of the loss. Florida insurance laws and requirements may change.